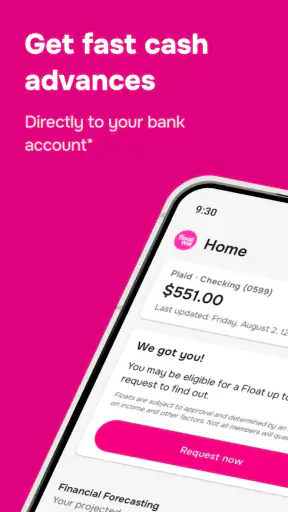
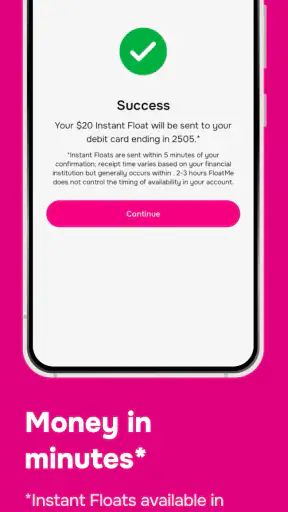
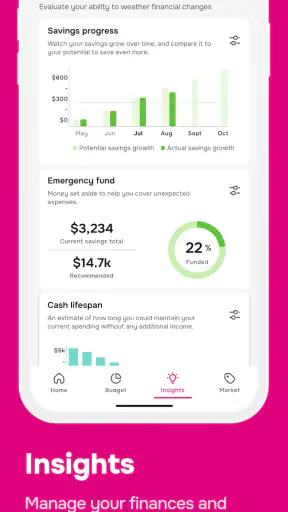
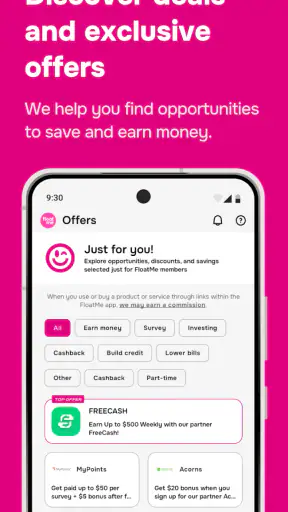
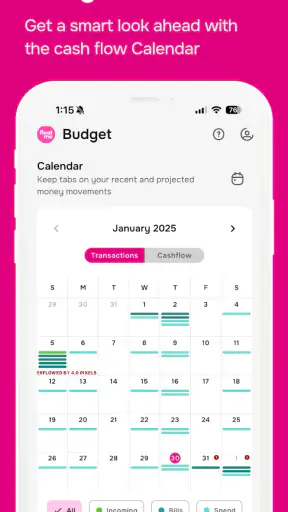
When money is tight between paydays, the hardest part is often not deciding what to buy; it is getting through a short gap without turning a small problem into expensive debt. FloatMe: Fast Cash Advance App is built for that narrow situation. I see it as a short-term finance tool rather than a complete budgeting system, a bank replacement, or a long-term borrowing solution. Its main appeal is the possibility of requesting a cash advance without interest or a credit check, which can make it feel less intimidating than a traditional loan application.
I spent time looking at the app from the point of view of someone who needs help with an ordinary expense, such as groceries, transport, or a bill arriving before payday. The experience is most useful when the need is temporary and the user can plan around the next incoming paycheck. It becomes much less suitable when the underlying issue is a recurring shortfall. That distinction matters more here than the attractive idea of “fast cash.”
Where the experience can become confusing
The first thing I would tell a friend is not to treat FloatMe as an instant, unconditional source of money. A cash advance app still needs to review the information connected to your account and determine whether the service fits your situation. Even when the application feels simple, eligibility and account setup can create pauses that are frustrating if you are already dealing with an urgent expense.
That is where many users can get stuck. A person may expect to open the app, request money, and finish immediately, while the actual process depends on entering accurate personal and financial details. A mismatch in names, account information, or employment-related details can slow things down. My practical advice is to begin the process when you have a few quiet minutes, not while standing in a checkout line or trying to solve a problem at the last second.
FloatMe is a finance app for short-term cash-flow gaps, not a conventional personal loan marketplace. That difference affects how I would use it. A regular loan is usually considered over a longer repayment period and may involve interest, credit checks, or a formal application. FloatMe’s appeal is more immediate: it is aimed at helping a user bridge the distance to payday. The trade-off is that the user must be especially disciplined about repayment timing.
The app is free to install, and its content rating is Everyone, which makes it approachable for a broad audience. That does not mean every financial situation is appropriate for it. Age suitability in an app store is not the same thing as financial suitability. I would still read each screen carefully, understand the repayment arrangement, and avoid agreeing to anything I cannot comfortably manage.
Another point worth keeping in mind is that “no interest” does not automatically mean “no cost in every possible sense.” Financial apps can have optional services, membership arrangements, expedited delivery choices, or other terms that affect the overall experience. I would never rely on the short summary alone. Before confirming a request, I would inspect the final amount, timing, and any clearly displayed charges inside the app.
Why a request may not move forward
If an advance request does not progress, I would first separate a technical problem from an eligibility or account issue. A frozen screen, repeated loading, or a button that does nothing may point to connectivity, an outdated installation, or a temporary app problem. A clear message about verification or account information is different: it usually means the next step is to review what was entered rather than repeatedly tapping the same control.
FloatMe is developed by FloatMe, and the current version is 8.21.0. The app has been available since October 4, 2018, and supports Android 7.0 or later. Those details are useful when troubleshooting an older phone. If the device is running a compatible system but the app behaves strangely, I would still check whether the application itself is current, restart the device, and try again on a stable connection.
I would also avoid switching rapidly between several devices during setup. That can make it harder to tell whether the issue comes from the account, the phone, or the connection. A cleaner workflow is to use one device, close other demanding apps, and complete each screen carefully. This is not glamorous advice, but it prevents a surprising amount of confusion in financial applications.
Setup checks that save time
Before opening FloatMe, I would prepare the information needed to identify myself and connect the relevant financial account. I would make sure the details match exactly, including spelling and basic personal information. Small inconsistencies that seem harmless in another app can matter more when money is involved.
I would also check that the account I intend to use is active and accessible. If I recently changed banks, changed login details, or opened a new account, I would not assume the transition is invisible to the app. A cash advance workflow depends on reliable account information, so an old or rarely used account may create unnecessary friction.
A useful habit is to read every confirmation screen from top to bottom before continuing. I would look for the amount being requested, the expected repayment date, and the way the money will be delivered. I would also note whether the app presents optional speed or membership choices separately from the basic request. The goal is to know exactly what I am accepting rather than treating every highlighted button as part of one unavoidable process.
Notifications and account access can also affect the experience. If the app asks me to verify something, I would check the email address or phone number associated with the account and look in filtered message folders if a code does not appear. I would not share a verification code with another person or enter credentials into a message link that I did not intentionally initiate.
For privacy, I would install the app from the official Android or iOS store and avoid unofficial copies. Finance apps deserve the same caution as banking apps. I would keep the phone protected with a screen lock, avoid using public Wi-Fi for sensitive account work when possible, and sign out or secure the device if someone else regularly uses it.
A better way to plan the first request
The safest first use is a small, clearly defined need that can be covered by the next paycheck without affecting rent, utilities, food, or other essential commitments. I would write down the expected repayment date before requesting anything. Then I would subtract the repayment from my next paycheck on paper. If that leaves the budget short, the advance is not solving the problem; it is moving the problem a few days forward.
Here is the everyday scenario where I think FloatMe makes the most sense. Suppose an unexpected pharmacy purchase arrives shortly before payday, and the user knows the next paycheck is already scheduled and mostly allocated. The app may offer a way to cover that immediate gap without applying for a conventional loan or undergoing a credit check. I would still compare the requested amount with the upcoming budget and refuse to borrow more simply because the interface makes it available.
The less healthy scenario is using one advance to cover the repayment of another advance or relying on the app every pay cycle for groceries. In that situation, the issue is not timing but income and expenses. A conversation with a bill provider, a revised spending plan, or a longer-term financial resource may be more appropriate. FloatMe can be convenient, but convenience should not disguise a structural budget deficit.
Recovering when the workflow breaks
If the app stops responding during setup, I would begin with simple steps: confirm the internet connection, close and reopen the app, restart the phone, and check for an available update. I would avoid repeatedly submitting the same request while unsure whether the first attempt went through. Duplicate actions are especially risky in financial workflows because they can create uncertainty about what is pending.
After reopening the app, I would look for a request status, confirmation message, or account activity record before trying again. If the app shows that a request is already being processed, patience is safer than pressing the request button repeatedly. I would save any confirmation details that appear, such as an on-screen reference or message, without posting them publicly.
If a connection step fails, I would carefully recheck the account credentials and make sure I am using the correct financial institution or account. I would not guess at passwords over and over, because repeated failed attempts can lock an account independently of FloatMe. If the problem appears to be with the bank’s own login or security process, I would resolve that directly through the bank’s official channel.
When an identity check does not complete, the best response is usually accuracy rather than improvisation. I would review the information for typing errors, ensure documents or images are readable if the app requests them, and try again under good lighting with a stable connection. I would not edit information simply to make an application pass. Financial verification is one area where honest, consistent details matter more than speed.
For a persistent problem, I would use FloatMe’s in-app support route or the official support channel associated with the service. I would describe the exact point of failure, the device system, and any message shown. I would never include a full password, security code, or unnecessary account number in a support request. A short, precise report is more useful and safer than a long message containing sensitive information.
When waiting is the correct recovery step
Not every delay means the app is broken. Account verification, bank connectivity, and payment processing can involve steps outside the app itself. If the screen clearly says that something is being reviewed or processed, I would avoid uninstalling the application immediately. Removing it can erase useful context from the device and make it harder to follow the original request.
I would also keep enough money available in the repayment account for the agreed date. This is one of the most important practical details. A user who receives help before payday but forgets the repayment can face a new financial problem, even if the original request was sensible. I would set a personal calendar reminder and check the account before the scheduled withdrawal or repayment.
If the expected money does not arrive, I would first confirm the request status and destination account rather than assuming the funds are lost. I would check whether the account information changed, whether the transaction is still pending, and whether a notification was missed. Only after that would I escalate to support. Keeping a simple timeline of what happened makes the conversation much easier.
When FloatMe is not the cause
Some apparent app failures are really account or device problems. A bank may be unavailable, a password may have expired, a phone may have too little storage, or a security setting may block a required step. If other financial apps or the bank’s own application are also failing, I would investigate the device or financial institution before blaming FloatMe.
There is also a difference between being unable to request an advance and disliking the result of an eligibility decision. The first may be technical; the second is part of how the service evaluates requests. I would not create multiple accounts or submit inconsistent information to work around a decision. That can make a financial profile harder to resolve and is not a responsible troubleshooting method.
The app’s popularity suggests that many people find it useful. It holds an average rating of 4.5 from around 77 thousand ratings, and it has passed the one-million-install mark. I read those numbers as evidence of broad interest, not as a promise that every user will receive the same outcome. Personal banking arrangements, income timing, account history, and device conditions can all change the experience.
Compared with a credit card, FloatMe may be preferable for someone who wants to avoid adding a revolving balance and does not want a credit check for a short gap. Compared with a traditional personal loan, it is more focused and less suited to a large expense or a repayment plan extending over months. Compared with an overdraft, it may offer a more deliberate request process, although the user still needs to understand the timing and any applicable terms.
A budgeting app may be a better choice when the real need is visibility rather than emergency cash. A bank savings buffer is better when the user can build one gradually. A bill negotiation or payment-plan request is better when the expense is recurring. I would choose FloatMe only when the need is temporary, the repayment is realistic, and the alternatives are less suitable for that specific moment.
One subtle trade-off is psychological: easy access can reduce the hesitation that sometimes protects people from unnecessary borrowing. I would therefore create a personal rule before using the app, such as requesting only the exact amount needed for one essential expense and not treating the available amount as a spending limit. That rule is more valuable than any clever button or shortcut.
Who should use it carefully
FloatMe may suit a person with predictable income, a temporary timing mismatch, and enough room in the next paycheck to repay the advance comfortably. It can also appeal to someone who wants to avoid a credit check and prefers a focused cash-flow tool over a conventional loan application.
I would be cautious if income changes from week to week, if several bills are already overdue, or if the next paycheck is committed to essentials. I would skip it if borrowing has become a repeated part of the monthly budget. In those situations, the app may provide immediate relief while increasing pressure later.
I would also avoid using it for discretionary purchases that can wait. The absence of interest does not remove the responsibility to repay. A delayed restaurant meal, upgrade, or impulse purchase is not the same as an unavoidable short-term need, and the convenience of the app should not blur that line.
My practical verdict
After considering both the useful case and the frustrating one, I see FloatMe as a narrowly focused tool with a clear place in a careful budget. The promise of cash advances without interest or credit checks is meaningful for someone facing a brief gap before payday. The free price and broad Everyone rating make the app easy to approach, while its established presence and large user base make it feel less experimental than a brand-new finance product.
Still, I would not install it expecting guaranteed instant money. The setup may require accurate account information, verification, and patience when a bank connection or review step takes time. The safest workflow is to prepare before an emergency, request only what is necessary, confirm the repayment plan, and keep enough money available when that repayment is due.
My strongest recommendation is to use FloatMe as a bridge, never as a foundation. If it helps once with a well-understood timing problem, it can be practical. If you need it repeatedly, that is a sign to look beyond the app and address the budget itself. The right question is not “Can I get an advance?” but “Can I repay it without creating the next emergency?”
For that reason, I would recommend FloatMe to financially organized users who need a temporary solution and are willing to read the details carefully. I would point someone with ongoing debt, unstable income, or no repayment room toward a different form of support. Used with restraint, it can fill a small gap; used casually, it can make a larger gap harder to escape.


